Health Insurance Options for Laid-Off Workers Too Young for Medicare
Older workers who lose their jobs face a difficult gap in health coverage before Medicare eligibility at 65. Here are the key options to consider.
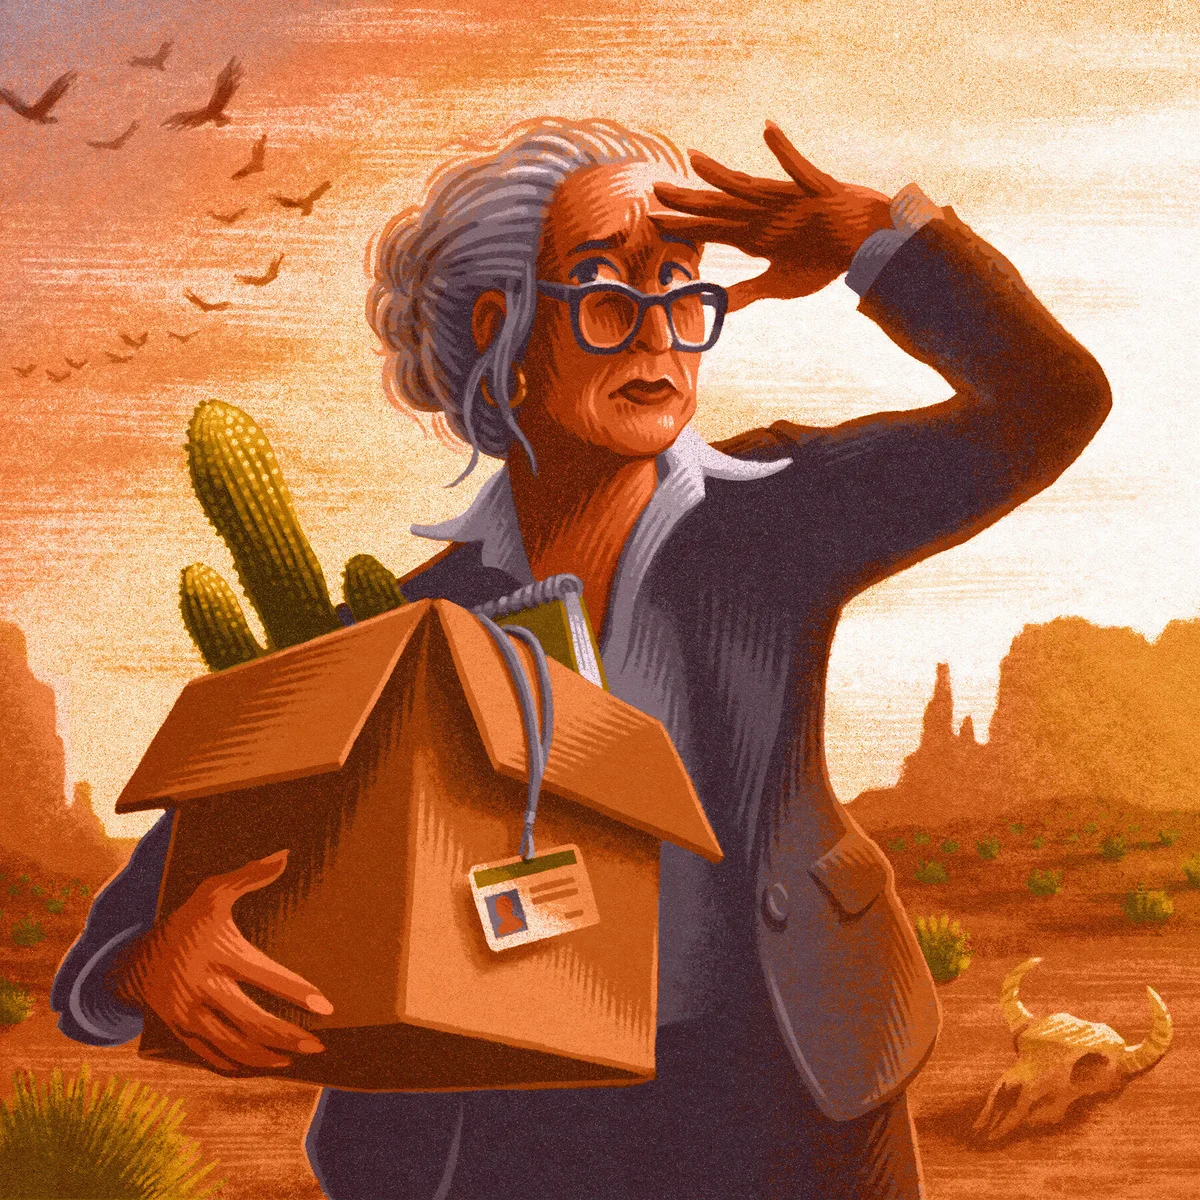
For older Americans who find themselves suddenly unemployed, one of the most pressing concerns is securing health insurance during the years before they qualify for Medicare at age 65. This coverage gap can be financially and logistically challenging, leaving many scrambling for viable alternatives in a complicated insurance market.
COBRA continuation coverage is typically the first option available to recently laid-off workers. It allows individuals to remain on their former employer's health plan, but the cost can be steep — workers must pay the full premium, including the share previously covered by the employer, plus an administrative fee. While COBRA provides continuity of care, it is generally regarded as a short-term stopgap rather than a sustainable long-term solution.
Read more Oil Prices Fall Further as U.S.-Iran Diplomacy Advances →
The Affordable Care Act marketplace offers another avenue. Depending on income level, laid-off workers may qualify for premium subsidies that make marketplace plans significantly more affordable. A job loss counts as a qualifying life event, triggering a special enrollment period outside the standard annual window, which gives displaced workers an opportunity to shop for coverage promptly.
For those whose income drops substantially after a layoff, Medicaid may become an option, depending on the state of residence. Eligibility thresholds vary widely, and some states have expanded Medicaid under the ACA, broadening access for low- and moderate-income adults. Consulting a licensed insurance broker or a state navigator can help laid-off workers assess which program best fits their circumstances and budget.
The challenge is particularly acute for workers in their late 50s and early 60s, who may face years of coverage gaps before Medicare kicks in — and who statistically encounter more difficulty returning to employer-sponsored coverage through a new job. Planning ahead and understanding all available options is critical for this demographic. Continue reading at NYT > Business.